Accounting Guide for Private Clinics & Walk-In Practices
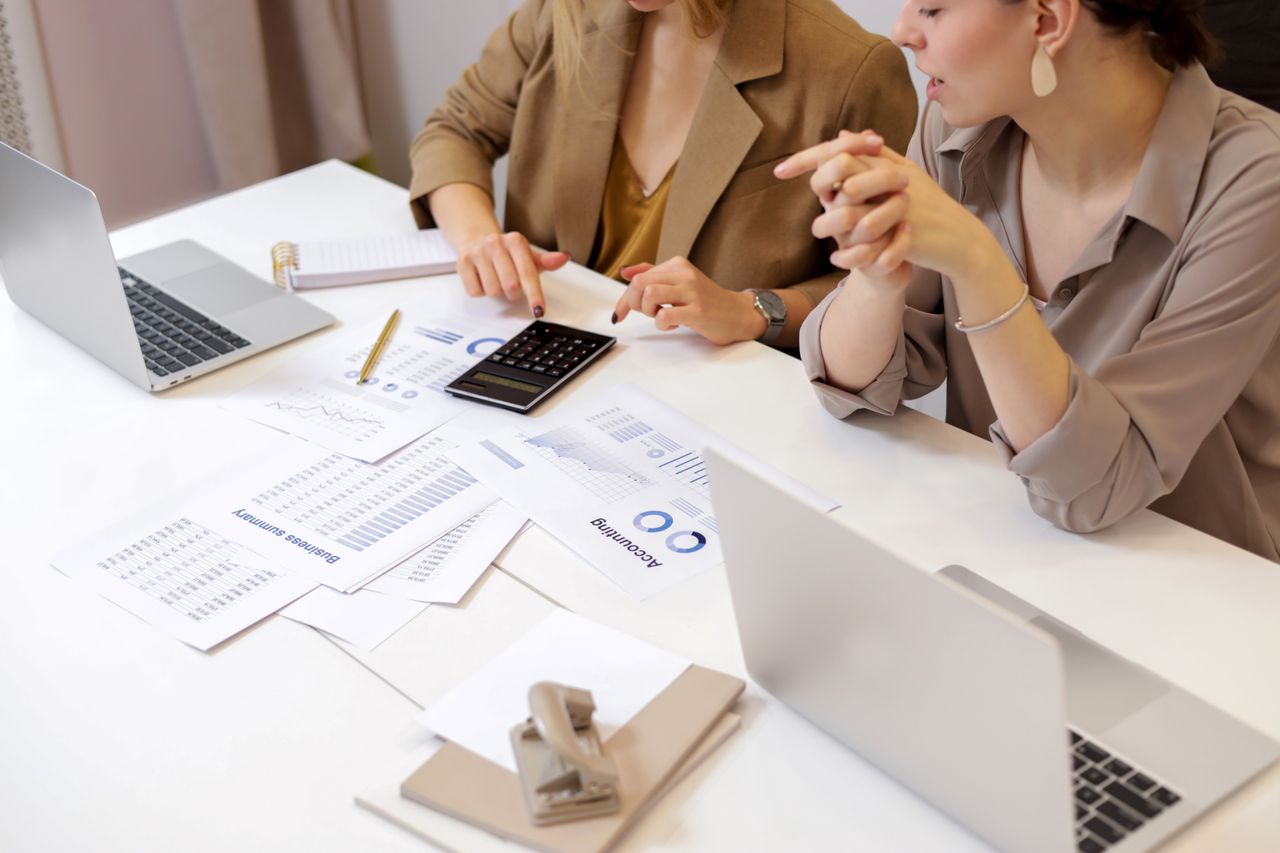
Running a private clinic or walk-in practice involves far more financial activity than simply collecting payments from patients. Physician compensation, payroll, medical supplies, clinic overhead, insurance payments, GST/HST considerations, equipment purchases, and professional expenses all need to be recorded accurately. A well-organized accounting system gives clinic owners a reliable view
Running a private clinic or walk-in practice involves far more financial activity than simply collecting payments from patients. Physician compensation, payroll, medical supplies, clinic overhead, insurance payments, GST/HST considerations, equipment purchases, and professional expenses all need to be recorded accurately. A well-organized accounting system gives clinic owners a reliable view of profitability while helping them meet their tax and reporting obligations in Canada.
Separate Clinical Revenue From Other Income
Private clinics can generate revenue through several channels. Patient fees, insurance reimbursements, third-party contracts, occupational health services, medical assessments, and other professional services may all appear in the practice’s financial records.
Each revenue source should be recorded consistently rather than deposited into the same account without supporting details. Maintaining clear documentation makes it easier to reconcile deposits, identify outstanding amounts, and determine how different areas of the practice are performing.
Physicians should also distinguish clinical revenue from non-clinical income. For example, rental income from providing space to another practitioner may have different accounting and tax considerations than professional medical fees.
Maintain Separate Business and Personal Accounts
Clinic owners should keep business banking and personal finances separate. Using one account for both creates unnecessary bookkeeping complications and makes it harder to establish which transactions relate to the practice.
A dedicated business account should receive clinic revenue and cover operating expenses wherever possible. Business credit cards can similarly provide a clear record of purchases such as medical supplies, software, professional memberships, advertising, office equipment, and other legitimate practice costs.
For incorporated physicians, maintaining clear separation becomes particularly important because the corporation is a distinct legal entity. Personal withdrawals, shareholder transactions, and business expenses should be properly classified rather than casually mixed together.
Track Payroll and Physician Compensation Carefully
Payroll can represent one of the largest expenses for a private clinic. Receptionists, medical office assistants, nurses, clinic managers, and other employees may all require regular payroll processing and appropriate source deductions.
Clinic owners should maintain accurate records of wages, vacation pay, employer contributions, benefits, and payroll remittances. CRA requires employers to withhold and remit amounts such as income tax, Canada Pension Plan contributions, and Employment Insurance premiums where applicable. Payroll records should therefore be reconciled regularly rather than reviewed only at year-end.
If physicians work through different arrangements, compensation should also be documented according to the actual relationship. Employees, independent contractors, and physicians operating through professional corporations can have different reporting implications.
Categorize Medical and Operating Expenses
A clinic’s expense structure can be extensive. Common categories may include:
- Medical and clinical supplies
- Office rent and common-area costs
- Staff wages and benefits
- Medical equipment
- Computer hardware and software
- Telephone and internet services
- Professional insurance
- Licensing and registration fees
- Accounting and legal services
- Advertising and marketing
- Cleaning and maintenance
- Continuing professional education
Accurate categorization matters because expenses may receive different accounting and tax treatment. Current operating expenses are generally treated differently from capital purchases such as significant medical equipment or long-term assets.
A CPA for physicians can help establish an expense structure that reflects the clinic’s actual operations and keeps supporting documentation organized for tax reporting.
Understand GST/HST Obligations
GST/HST is an area where private medical practices need to be particularly careful. Certain healthcare services can be exempt from GST/HST when specific conditions are met, while other services may be taxable depending on their nature and circumstances.
For example, a medical practice may provide services that fall under different GST/HST rules, particularly if it offers assessments, reports, cosmetic services, consulting, or other non-traditional medical services.
Do not assume that every service offered by a medical professional receives identical GST/HST treatment. The nature of the service, its purpose, and the applicable exemption can matter. Clinics should maintain records that allow taxable and exempt activities to be identified separately when necessary.
Keep Track of Accounts Receivable
Walk-in practices may receive payments immediately, but private clinics can have significant receivables when billing third parties, insurers, corporations, or other organizations.
An accounts receivable system should show the invoice date, payer, amount outstanding, payment status, and follow-up history. Reviewing this information regularly helps prevent overdue balances from disappearing into the background.
A clinic may also need to reconcile insurance or third-party payments against the original billing records. Differences should be investigated rather than automatically written off.
Manage Equipment Purchases Properly
Medical practices frequently invest in equipment ranging from diagnostic devices and examination equipment to computers, treatment tools, and specialized technology.
Large purchases should not automatically be treated as ordinary operating expenses. Depending on the nature and cost of the asset, accounting and tax rules may require capitalization and depreciation or capital cost allowance treatment.
Keep invoices, purchase agreements, financing documents, warranties, and payment records for significant equipment. These documents establish the original cost and provide essential support for the clinic’s accounting records.
Reconcile Financial Records Every Month
Monthly reconciliation should be a standard part of clinic administration. Compare accounting records against bank statements, credit card statements, payment processors, payroll records, and other financial documentation.
Regular reconciliation can identify duplicate transactions, missing deposits, incorrect expense classifications, unexplained withdrawals, and outstanding payments.
Waiting until tax season creates a much larger administrative burden. Monthly reconciliation keeps financial information current and allows clinic owners to address errors while the underlying transactions are still easy to trace.
Review Financial Statements Regularly
A clinic owner should understand what the financial statements are saying. A monthly profit-and-loss statement can show whether revenue is keeping pace with staffing, rent, supplies, technology, and other operating costs.
The balance sheet provides another perspective by showing assets, liabilities, and equity. Together, these reports can reveal changes in cash reserves, outstanding obligations, receivables, and the clinic’s overall financial position.
A CPA for physicians can also help interpret these reports and identify accounting issues that may deserve further attention before they affect year-end tax planning or business decisions.
Plan for Tax Obligations Throughout the Year
Tax planning should not begin weeks before the filing deadline. Private clinic owners should maintain organized records throughout the year and understand their expected tax obligations in advance.
Depending on the clinic’s structure, this may involve corporate income tax, personal income tax, payroll remittances, GST/HST filings, instalment payments, and other reporting requirements.
Keeping funds aside for anticipated obligations can also prevent a profitable practice from experiencing an unexpected cash-flow problem when taxes become due.
Build an Accounting System That Scales
The accounting needs of a solo physician differ from those of a multi-provider clinic. As a practice expands, financial processes should evolve with it.
Cloud-based accounting software, integrated payment systems, payroll platforms, digital receipt management, and automated bank feeds can reduce repetitive administrative work. However, automation does not eliminate the need for accurate categorization and regular review.
Working with a CPA for physicians can provide additional oversight when a practice becomes incorporated, adds practitioners, expands locations, purchases substantial equipment, or develops multiple revenue streams.
Strong clinic accounting is ultimately about maintaining accurate financial information throughout the year. When revenue, expenses, payroll, receivables, taxes, and assets are recorded systematically, physicians have a clearer understanding of how their practice is performing and can make financial decisions based on reliable information.
Need expert help with your taxes?
Similar Blogs
Accountants Help Healthcare Practices Grow Faster
Growing a healthcare practice requires more than attracting new patients. Dentists, physicians, physiotherapists, chiropractors, and other healthcare professionals also need…